Financial advisers should rethink their approach to selling insurance and instead position themselves as buyers’ advocates, according to MDRT lifetime Top of the Table member Guy Mankey.
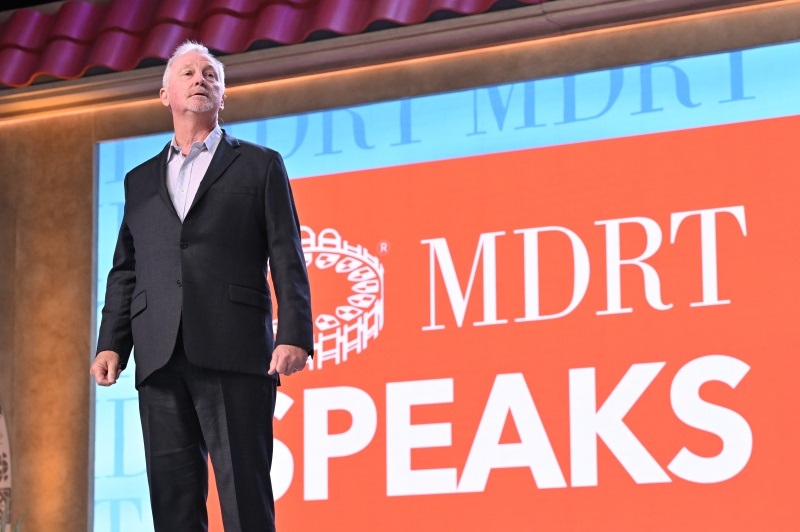
Speaking at a joint MDRT Oceania online presentation attended by more than 70 Australian and New Zealand advisers, Mankey outlined the approach he has developed during more than four decades in the insurance industry, including how he helps clients prioritise cover, manage premiums and make informed decisions.
Having started his career in 1979, Mankey said one of his most important lessons was recognising that clients did not want to be sold insurance. “I buy insurance,” he now tells people when asked what he does for a living.
He explained that changing the conversation from selling insurance to buying it on behalf of clients fundamentally alters the adviser-client relationship.
“I’m basically a buyer’s advocate,” he said.
“We’ll figure out what you might need, and I’ll help you buy it the best way possible.”
Mankey said advisers should remember there are three parties in every retail insurance transaction – the client, the adviser and the insurer – and that the client’s interests must always come first.
Claims Experience Shapes Advice
Drawing on his own claims experience, Mankey said he had recorded almost $70 million in insurance claims over the past 16 years, including approximately $35 million in life claims and $14 million in critical illness claims.
He uses these figures to demonstrate the value of insurance and the importance of arranging cover while clients are healthy.
People don’t buy insurance with money. People buy insurance with good health…
“People don’t buy insurance with money. People buy insurance with good health,” he said.
He also emphasised that insurance advice should begin with an acknowledgement that clients have limited budgets.
Rather than recommending an ideal level of cover that may be unaffordable, he asks clients whether they have an unlimited insurance budget.
When they inevitably say no, he explains that prioritisation and compromise will be necessary.
I do not tell people what to buy. I just help them buy it…
“I do not tell people what to buy. I just help them buy it.”
His approach involves distinguishing between essential financial needs and additional wants, then presenting different sums insured and premium options so clients can make their own decisions.
Mankey said this process also helps protect advisers against potential future disputes over whether sufficient cover was recommended.
Rethinking Income Protection
One area where Mankey believes advisers can deliver better value is income protection.
He questioned the widespread preference for shorter waiting periods, suggesting clients may benefit more from directing premium savings towards longer benefit periods or additional critical illness cover.
Using an example of a client earning $20,000 a month, he compared the financial consequences of a 30-day waiting period with a 90-day alternative.
While the longer waiting period could mean foregoing two months of benefits, he argued that the additional premium required for shorter waiting periods may be difficult to justify for clients with sufficient savings.
He also highlighted the potentially substantial difference between income protection policies offering two-year, five-year or longer benefit periods.
The key, he said, is helping clients understand the financial trade-offs rather than automatically selecting conventional policy settings.
A Different Approach to Trauma Cover
Mankey also placed considerable emphasis on critical illness insurance, particularly its role in helping clients manage the financial consequences of cancer.
He said cancer accounted for the overwhelming majority of critical illness claims in his experience.
Beyond medical expenses, he encourages clients to consider sufficient cover to provide six to 12 months of income, allowing them greater flexibility during recovery.
He also suggested that paying off mortgage debt following a serious illness could significantly reduce financial pressure and provide more options when returning to work.
Timing Reviews Around Birthdays
Another practical strategy Mankey pointed to was scheduling insurance reviews around clients’ birthdays rather than policy anniversaries.
He argued that arranging new cover immediately before a birthday can deliver substantial premium savings where age-based pricing applies.
Using one example, he calculated that arranging $2.7 million in life cover just before, rather than just after, a client’s 60th birthday could produce premium savings of approximately $48,000 over 10 years.
Mankey said he generally schedules reviews around two months before the birthday of the person paying the most premiums, which allows ample time to make any required changes prior to the birthday.
He said his role was not to dictate how much cover clients should purchase, but to help them make informed decisions about the level of protection they could comfortably afford.