
There was strong interest this week in a global report finding that nearly half of Australian consumers considering life insurance feel confused and unconvinced…
Nearly half of Australian consumers considering life insurance feel confused and unconvinced by what they encounter, according to a new global report, with many abandoning the purchase before it is complete.
The World Life Insurance Report 2027, researched jointly by the Capgemini Research Institute and US-based global insurance and financial services trade association, LIMRA, surveyed more than 6,000 consumers worldwide, including 425 in Australia. It found 47% of Australian consumers considering a policy feel confused, uncertain or unconvinced by the information they find – higher than the 42% recorded globally. Across all markets, one in four consumers drop out of the purchase journey before completing it.
Confusion and cost top the list of barriers
The report points to overly technical language, affordability concerns and a perceived lack of relevance to a consumer’s life stage as leading barriers to purchase, where key findings included:
- 39% of Australian consumers cited cost as a barrier (35% globally),
- 28% cited a lack of clarity and transparency on coverage and policy terms (30% globally)
- 26% said life insurance was not relevant to their current life stage (25% globally)
…the affordability barrier is often a matter of perception rather than actual cost
LIMRA’s research suggests the affordability barrier is often a matter of perception rather than actual cost. “Our research shows affordability is often a perception problem – consumers believe life insurance costs far more than it does – and that makes education the industry’s biggest opportunity,” said Bryan Hodgens, Senior Vice President and Head of LIMRA Research. “We need to bring consumers into the fold and guide them through the entire process, keeping it simple, embracing tools like AI, but never losing sight of how essential human advisors are.”
Contact drops away after the sale
The report also found that consumer engagement often falls away once a policy is issued.
- 41% of Australian policyholders said they rarely or never hear from their insurer after purchase, compared with 36% globally
- 76% said the only contact they received related to billing and renewals
- 42% of discontinue their cover within three years of purchase
“When it comes to life insurance, [consumers] recognise its importance, but complexity at the point of purchase and post-sale silence undermine policy ownership – putting customer relationships at risk and triggering exits that cost the industry billions,” said Samantha Chow, Global Leader for Life Insurance, Annuities and Benefits Sector at Capgemini.
AI enters the research process, but advisers remain central
The report identified generative AI as a growing part of the research process, with around half of consumers globally planning to use such tools to discover and compare life insurance products, though two-thirds said they still prefer working with a human adviser when finalising coverage decisions.
Opportunities for Advisers
The report frames several of these gaps as openings for insurers and advisers. In the workplace, 48% of Australian employees had not formally assessed their employer-provided coverage yet reported feeling moderately confident in it – a combination that can leave people with a false sense of security and gaps in protection they are unaware of.
On retention, 48% of consumers say they would be more likely to stay with an insurer that offers proactive guidance before, during and after purchase, suggesting ongoing contact as a lever against early discontinuation.
Where Australia performs well
Australian employees fared better than the global average on one measure. More Australian employees receive coverage adequacy guidance through group insurance than the global average (34% compared with 25% globally), which the report said supports better-informed coverage decisions.
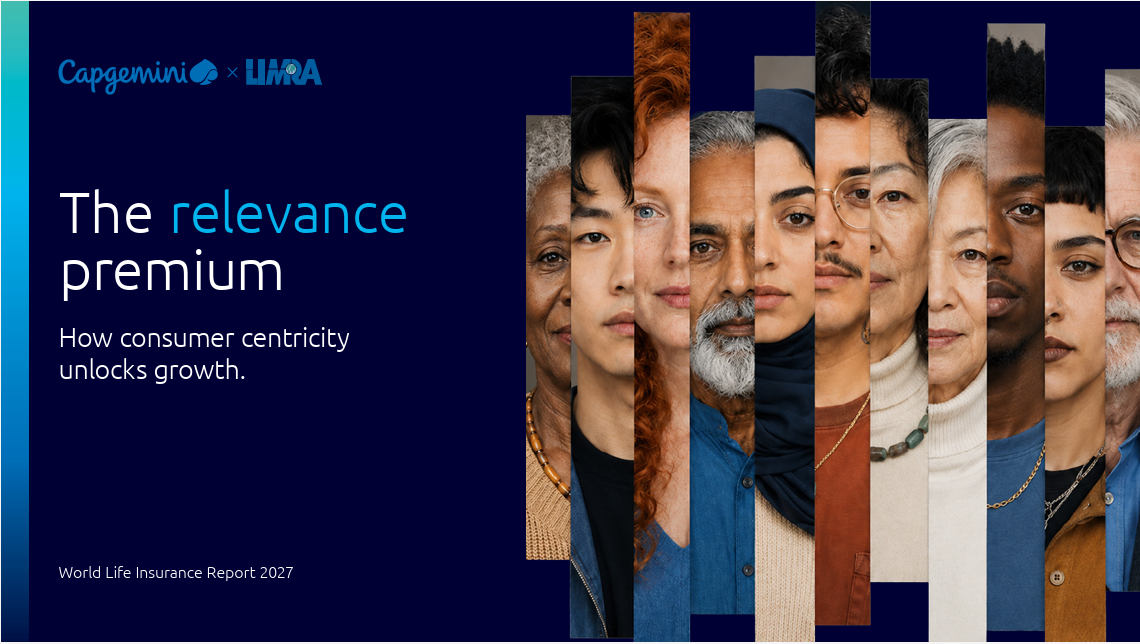
Click here or on the image below to access Capgemini/LIMRA’s The World Life Insurance Report 2027, entitled The relevance premium: How consumer centricity unlocks growth.
The scary part of this article is that 42% of customers cancel their policies within 3 years of purchase.
This is not new, as it has always been that high if there is no Adviser to keep up the conversation around the importance of their cover, though with the huge amount of money spent by Life Insurers on attaining New Business, it cannot be profitable if nearly half the revenue disappears in such a short period and it holds up the view that people need constant contact with an Adviser to maintain their coverage for the long haul.
Life Insurance has always been a grudge purchase and today's population is even more distracted with the constant bombardment of media feeds, so Life Insurance becomes another thing to think about when things settle down, which it NEVER does.
The Life Insurers are finally recognising that they have a problem, though they are either ignoring the biggest issue, or hoping for the problem to sort itself out, which it NEVER will and that problem is the over 50's customers who pay the most premiums, who WILL be cancelling their policies within 1 to 5 years due to sky rocketing premiums and no longer the need for the cover.
That cannot be solved as these customers will be cancelling, no matter what the Insurers do, which means substantial increases of true New Business that sticks on the books, is the ONLY solution, something the Life Insurers are failing miserably at.
Well indeed, the pigeons are coming home to roost, as advisers have always said they would, when the insurers developed LIF. At 66% of first year premium risk advisers really can’t afford to be spending time following up and educating new clients on a personal basis, and in a regular pattern.
And it’s particularly relevant where lapses are being induced because insurers are practising Duration-Based Pricing, effectively misleading purchasers of insurance as to future costs.
And now, thanks to Minister Molino, seeking to protect his mates in the super funds, we are about to empower life insurers to be able to “advise” directly the clients which have been initially placed with those insurers by personal-advice advisers. The insurers wouldn’t have those clients of it were not for advisers, because no one is going to ring up an insurer and say “I think I need some insurance”, unless of course they have a pre-existing health condition.
Anyone who thinks that life insurance companies are going to take the time to explain to “sticker shock” complaining clients exactly how insurance works, and more importantly how the insurance that the client currently holds is still relevant to their particular needs, should have their mind examined, as my parents used to say. To quote Darryl Kerrigan from “The Castle”, “tell them they are dreaming”
As I understand the proposal, this new range of advisors that will be employed by life insurers will be acting under the General Advice regime, long favoured by ASIC for corporate advice i.e big banks and big insurers. The Minister is going to create an environment where disgruntled life insurance policyholders, who choose to contact an insurer direct to complain about rapid increases in their premiums, will be setting themselves up to be fleeced.
I’ll bet London to a brick on that insurers will not do what advisers would do in such circumstances, and seek to firstly review the accuracy of the sum insureds, or then seek to modify covers to bring the premiums within the affordability range of that particular client in their particular circumstances. No way, José, because that would venture from general advice into the personal advice regime.
Sadly, in the absence of mutuals, insurers are motivated by shareholder value and its attachment to CEO bonuses. They have no obligation to always act in the best interests of the complaining policyholder. When an insurer is contacted by a disgruntled client, I suggest it will be a given that the insurer will seek to at least preserve some, or at least a good proportion, of the existing premium income. It’s simply a preservation strategy.
Insurers will probably achieve that objective by offering what appears, to an un-advised policyholder, to be a similar policy at a lesser premium, but in practice the new policy offering will be stacked with added severity and accordingly no longer meets the client’s needs. Policyholders will be seduced by the reduced costs, and won’t know enough to ask the right questions of the insurer.
How will the client know any difference? It’s highly likely that the disgruntled policyholder, who approaches an insurer direct complaining about excessive premium increases, will no longer have a relationship with the initiating adviser, and therefore cannot seek independent advice of the new policy detail.
And finally, there’s the business risk to life risk advisers. Should an insurer, in seeking to provide a complaining policyholder with some sort of premium saving, then act to replace the existing policy with another policy of lesser quality, wouldn’t that be a policy cancellation. And if the policy is still within responsibility, wouldn’t that be a lapse for the adviser? None of that has been explained.
I know I will be accused of cynicism, but in almost four decades of advice I’ve seen it all.
Between Jeremy and Old Risky's comments I'm not sure there's much more that can be said. As usual those two industry stalwarts are both spot on the money, disconcertingly so. I am so very glad I left this nonsense arena 6 years ago at age 60 as I'd be beside myself with angst now, having to survive in the current deplorable, moribund and decaying environment. My only regret is I didn't leave 5 years before that but for a decade I told myself it would get better as all the ludicrous changes were taking shape over those years.
I've made peace with the fact I didn't stay until I was 70+, as I'd intended for many decades. I had planned 70+ at a time in my 40s when life companies appreciated and exulted advisers and the politicians left us alone. Rewards for effort was a core unquestioned belief of advisers back then – where has that gone? . . . away, with proper remuneration. Also I loved my clients, the industry (never became a profession sadly), me fellow advisers and even some of the life company execs (temporary as they were). All of that is the opposite now, the antithesis of where any self respecting risk adviser wants to be.
I can't fathom why, these days, any adviser over the age of 55 who is financially independent and who can sell his/her risk business for a fair price doesn't get out – it is only deteriorating more by the day as advisers are being driven out by legislation and life company indifference, not to mention the decimated, hollowed-out product range and commission scales. With all the wokeness it won't be too long at all before commissions go away completely. We all know risk advice fees in isolation don't work so what happens then? Get out friends, if you can, while the getting is good(ish).
Comments are closed.