The retail life industry is currently surviving on a small cohort of advisers to bring in new business, with less than 500 advisers writing 50% of Australia’s life policies in 2023, according to Adviser Ratings.
The research firm says that with 15,634 advisers in Australia at the end of June, in the last six months only 40% wrote a life insurance policy “…what was once a standard part of an adviser’s armoury when on-boarding a client or reviewing as a staple of their annual meeting.”
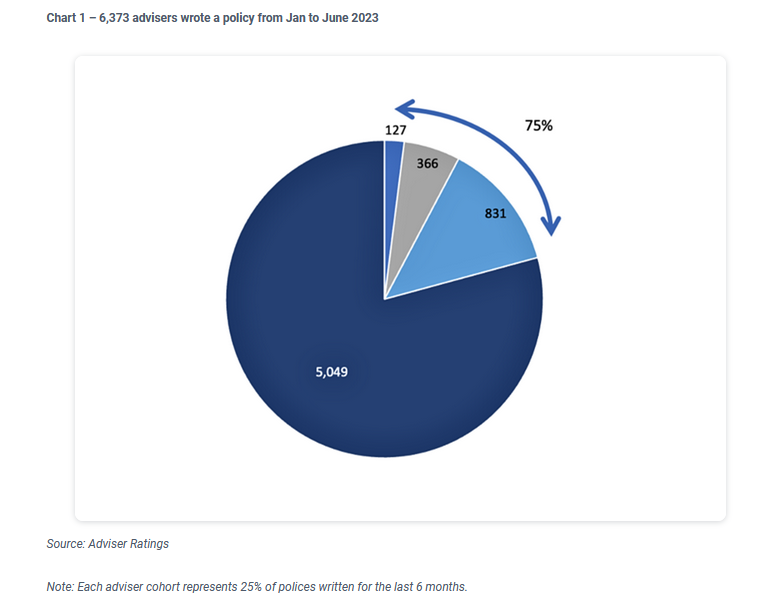
The Adviser Ratings chart below shows that 6,373 advisers wrote a policy from January to June 2023, highlighting that 127 advisers wrote 25% of policies and another 366 advisers wrote a further 25%, meaning only 493 advisers wrote 50% of the policies.
The chart also shows 831 advisers wrote a further 25% of policies with the last 25% of policies undertaken by 5,049 advisers.
 Adviser Ratings adds that as advisers “…have shifted to servicing more retirees and ‘riskies’ have fled in droves, underinsurance is worse than ever.”
It references Deloitte’s Mind the Gap report, estimating that Australian families could have claimed $25b more last year if not for underinsurance (see: Addressing the Underinsurance Gap).
…127 advisers, who write 25% of Australia’s retail life policies Are earning on average $200,000 – $250,000 in upfront commissions every year…
The research company also states that those 127 advisers, who write 25% of Australia’s retail life policies “…are earning on average $200,000 – $250,000 in upfront commissions every year, a significant drop from the earning potential prior to LIF.”
It says this begs the question “…if the top line is immovable, will broader technology solutions, the QoA Review or adviser recruitment help bridge the gap.”
Adviser Ratings also points to Deloitte’s estimate that the Australian life insurance industry could grow by up to $40b in annual premium by addressing the under-served segments of the market (again see: Addressing the Underinsurance Gap).
It says to achieve this, all stakeholders need to come together to find a viable solution.
“Technology and customer centricity will play a role, but government incentives such as rebates or tax deductibility on death insurance should also be on the table. And will super funds and group life play a larger role,” the firm asks.